VA Home Loans: Why Today's Market Could Be a Big Opportunity for Veterans
VA Home Loans: Why Today's Market Could Be a Big Opportunity for Veterans
If you're a veteran or active-duty service member thinking about buying a home, you may have more advantages than you realize!
VA home loans already offer some pretty incredible benefits. But with more homes available and buyers having more negotiating power in many markets, those benefits could go even further.
And if you've ever heard that VA loans are harder to get approved, take longer to close, or make your offer less attractive to sellers, you might be surprised by what the numbers actually show!
Let's break down what you should know about VA loans and why today's housing market could present some great opportunities.
The Benefits of VA Home Loans
Did you know that nearly 4 million veterans and service members currently have an active VA home loan?
According to the Department of Veterans Affairs, more than 343,000 homes were purchased using VA loan benefits during its most recently reported fiscal year.
And it's easy to understand why!
For eligible veterans and active-duty service members, VA loans offer some major advantages:
-
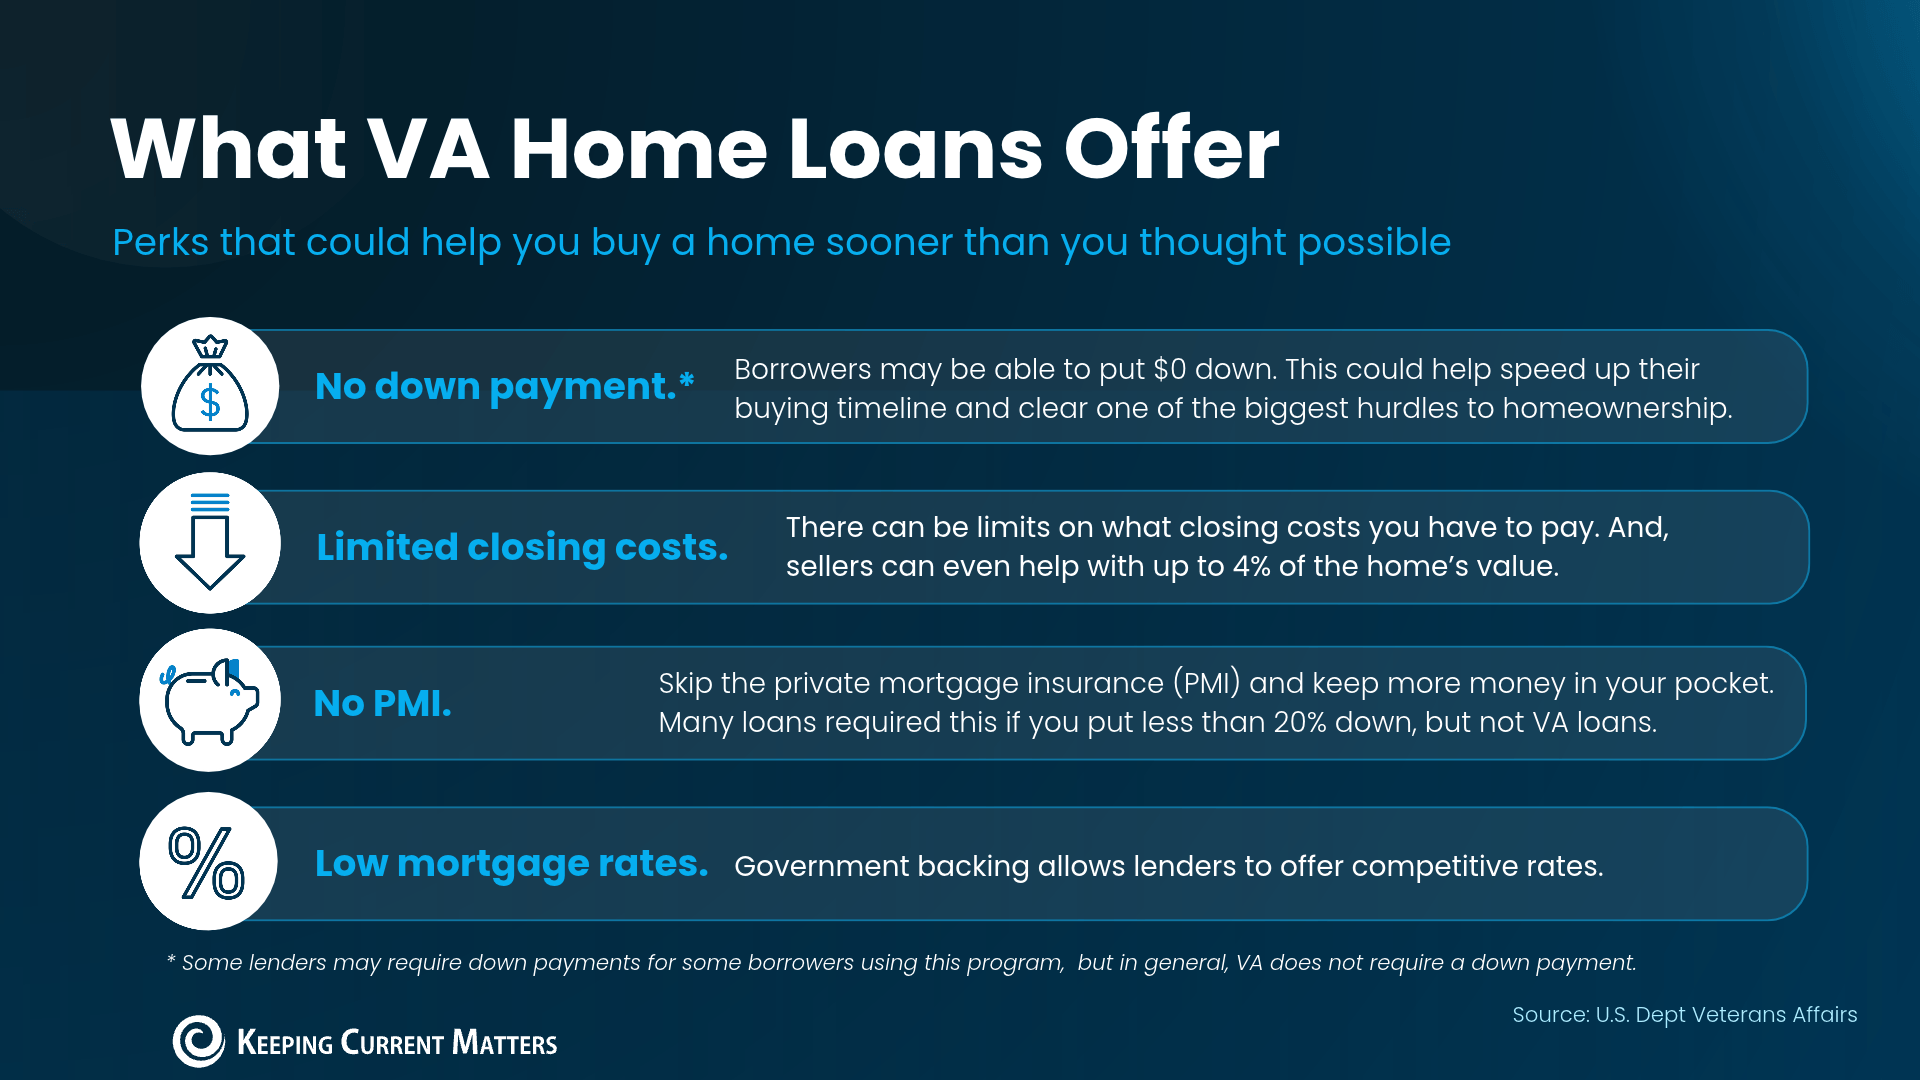
No down payment required: Many eligible borrowers can purchase a home without putting money down.
-
No monthly mortgage insurance: Unlike many conventional loans, VA loans don't require monthly mortgage insurance, even with no down payment.
-
Competitive interest rates: VA loans often offer attractive mortgage rates that can help make monthly payments more affordable.
These benefits can make a huge difference, especially for buyers who want to purchase a home without draining their savings.
And with VA loan usage increasing over the past two years, more veterans are taking advantage of these opportunities.
Keep in mind that VA loans may still have closing costs and a VA funding fee, unless you're exempt.
VA Home Loan Myths vs. Reality: What the Numbers Actually Show
One of the biggest misconceptions about VA loans is that they're more difficult to close.
A few years ago, when buyers were competing against multiple offers, VA financing sometimes faced an uphill battle.
In fact, a 2021 National Association of Realtors survey found that 89% of sellers were likely to accept an offer using conventional financing, compared to just 30% for offers using FHA or VA financing.
But were those concerns really justified?
A 2026 report from Vetted VA, using 2025 mortgage data, challenges several common misconceptions.
Myth #1: VA Loans Get Denied More Often
The reality? VA loans actually had the lowest denial rate among the loan types compared in the report!
Here's how purchase loan application denial rates compared:
-
VA loans: 8.2%
-
USDA loans: 12.5%
-
FHA loans: 12.8%
-
Conventional loans: 15.0%
That's right! VA loans had a lower denial rate than conventional, FHA, and USDA loans.
That doesn't mean every VA loan application will be approved, but it certainly challenges the misconception that VA financing is more difficult to obtain.
Myth #2: VA Financing Is Less Reliable
Here's another interesting statistic.
According to the same report, 90% of VA loan applications that reached underwriting made it to closing, compared to 81% of conventional loan applications.
That's a pretty significant difference!
For sellers considering an offer with VA financing, it's a good reminder that the type of loan alone doesn't determine whether a transaction will successfully close.
Myth #3: VA Appraisals Take Longer
Many people assume VA appraisals automatically slow down the homebuying process.
But according to the report, VA appraisals typically take approximately 7 to 10 business days, which is comparable to conventional and FHA appraisals.
Of course, every transaction is different, and timelines can vary depending on the property, lender, and appraiser.
Myth #4: Sellers Have To Pay All the Buyer's Closing Costs
This one comes up quite a bit!
The truth is that VA buyers can pay many of their own standard closing costs.
Buyers and sellers can also negotiate which allowable expenses the seller will cover.
So if you're selling a home in St. Charles Parish, don't automatically overlook an offer just because the buyer is using VA financing.
How VA Loans Could Help You Keep Thousands in Savings
Now, here's where things get really interesting!
With more homes available and less competition in many markets, buyers may have opportunities to negotiate that weren't as common a few years ago.
Depending on the property and local market conditions, that could include negotiating the purchase price, requesting repairs, or asking the seller to contribute toward closing costs.
And here's something many VA buyers don't realize!
VA guidelines allow sellers to cover the buyer's normal allowable closing costs, plus certain additional concessions of up to 4% of the home's reasonable value.
The 4% limit applies to specific seller concessions, not all ordinary closing costs.
Think about what that combination could mean for you!
You may be able to:
-
Purchase a home with no down payment.
-
Avoid monthly mortgage insurance.
-
Negotiate assistance with allowable closing costs.
-
Keep more of your savings available after purchasing your home.
That could mean keeping thousands of dollars in your savings instead of spending them upfront!
And let's face it, having that extra financial breathing room after purchasing a home is a pretty big deal.
Whether you're looking at homes for sale in Luling, Destrehan, or other communities throughout St. Charles Parish, understanding these benefits can help you make more informed decisions.
Of course, seller contributions aren't guaranteed, and every transaction is different. That's why having an experienced real estate agent and a knowledgeable lender working together is so important.
One More Thing Veterans Should Know About Choosing a Lender
Here's something I really want to point out because I think it surprises a lot of people.
Just because a mortgage company has "VA" in its name doesn't mean it's affiliated with the Department of Veterans Affairs!
VA home loans are offered through participating private lenders, including banks, credit unions, and mortgage companies.
And you aren't required to use a particular mortgage company just because its name or advertising makes it sound connected to the VA.
My advice? Shop around!
Compare interest rates, lender fees, closing costs, and the experience each lender has with VA financing.
Ask questions, understand your options, and make sure you're working with someone who knows the VA loan process.
The lender you choose can make a big difference in your overall homebuying experience.
Ready To Put Your VA Home Loan Benefits To Work?
If you're a veteran or active-duty service member thinking about buying a home in St. Charles Parish or the surrounding Louisiana communities, don't let misconceptions keep you from exploring your options.
Whether you're just getting started or you're ready to begin looking at homes, I'd love to help!
Now, I'm not a lender, but here at Brandy Nichols Realty, we've got some GREAT ones in our back pocket! 😉
We work with knowledgeable lenders who understand VA financing and can help explain your benefits, explore your options, and determine what you may qualify for.
And when you're ready to start house hunting, I'll be here to help you navigate the rest!
You've earned these benefits. Let's make sure you understand how to put them to work for you!
Brandy Nichols | Brandy Nichols Realty
📧 Brandy@BrandyNicholsRealty.com
📞 504.390.3381
📍 12715 Hwy 90 Suite 210, Luling, LA 70070
Sources for the statistics and VA loan information:
The statistics are national figures, not St. Charles Parish-specific data.
Categories
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "
GET MORE INFORMATION